So, you’ve done it.
You updated your CV, went through interviews, met with hiring managers, negotiated an offer, and accepted a new role.
There’s usually a mix of emotions at this stage: excitement, relief, and a sense that a new chapter is about to begin.
Then comes the part most people underestimate. You still need to resign.
For many professionals in financial services, accounting, and advice, this is actually the most uncomfortable stage of the entire job move.
Over the years, we’ve seen resignations unfold in very different ways. Some are smooth and professional. Others become emotional, unexpected, or quickly turn into negotiations.
In most cases, what happens next falls into a few common scenarios.
When Your Resignation is Accepted Immediately
Sometimes, employers respond to a resignation in a very direct and professional way. They accept it and move straight into transition planning.
In financial advice, accounting, and other client-facing industries, this can happen quite quickly due to confidentiality, compliance, and operational continuity requirements.
You may experience:
- Immediate acceptance of your resignation
- A shortened notice period
- Removal of system or client access soon after resigning
- Payment in lieu of notice
While this can feel abrupt, it is usually procedural rather than personal.
Businesses are managing risk, client continuity, and knowledge access.
The most important thing in this situation is to remain professional. How you exit often leaves a lasting impression, especially in smaller professional networks.
What to Expect During Your Notice Period
Once your resignation has been accepted, the focus usually shifts to handover and transition.
Depending on the business, you may be asked to:
- Document processes and workflows
- Handover clients or active work
- Train or brief replacement staff
- Finalise outstanding tasks or compliance items
For some people, the notice period feels normal. For others, it can feel slightly awkward after announcing they are leaving.
Best Practices During Your Notice Period
Your notice period is still part of your professional reputation, especially in industries like financial planning, accounting, and mortgage broking where networks are small and relationships matter.
A few simple things can make the transition smoother:
- Stay engaged and avoid mentally checking out too early
- Communicate professionally with colleagues and managers
- Complete handovers properly where possible
- Be mindful of confidentiality and client information
- Clarify final pay, leave balances, and equipment returns early
If you are moving to a competitor, it’s also worth reviewing any restraint or non-compete clauses in your contract so you understand your obligations before finishing up.
Insight
If your employment contract includes a non-compete or restraint clause, it’s important to review it carefully before moving to a new role. In financial services and client-facing industries, some contracts may place restrictions on contacting clients, joining competitors, or soliciting staff for a certain period after resignation. These clauses are not always enforceable in full, but they can still shape how your transition is managed, including immediate removal of system or client access once you resign.
When a Counter Offer is Made
This is probably the scenario most candidates expect once they resign.
After weeks or months of feeling stuck, suddenly the conversation changes very quickly. The salary increase that wasn’t possible before becomes possible.
Flexible work is suddenly open for discussion. A promotion, leadership pathway, or promises of future progression start getting mentioned.
For many people, this is the moment where doubt creeps in.
And to be fair, counter offers can feel good. It’s validating when your employer fights to keep you. Especially if you’ve invested years into the business or genuinely enjoy the people you work with.
But it’s important to take a step back and remember why you started looking in the first place.
Most professionals don’t go through the effort of updating their CV, attending interviews, and accepting another offer over one frustrating week. Usually, the decision has been building for a while.
It might have been:
- Feeling overworked or burned out
- Limited opportunities for progression
- Poor leadership or lack of support
- Ongoing frustration with culture or structure
- Feeling undervalued despite consistently performing well
- Wanting better flexibility or work-life balance
A counter offer can absolutely improve some of those things. Sometimes employers genuinely don’t realise there’s an issue until someone resigns.
But in other cases, the counter offer only fixes the immediate pressure point without changing the bigger reasons the employee became unhappy in the first place.
That’s why it’s important not to make the decision emotionally or too quickly. The better question is not “what are they offering me now?” but “where do I realistically see myself growing long-term?”
Why Employers Make Counter Offers
From an employer’s perspective, losing a team member creates disruption.
The cost of replacing staff can be significant, including:
- Recruitment and agency fees
- Training and onboarding time
- Productivity gaps during transition
- Impact on client relationships
- Pressure on remaining team members
Because of this, counter offers are often reactive rather than strategic. Sometimes employers genuinely recognise your value too late. Other times, it is simply an attempt to maintain stability while they work out longer-term staffing plans.
Salary is usually a major part of the conversation. Once an employee resigns, market rates and compensation benchmarks suddenly become more relevant.
Counter offers can work, particularly when an employee is generally happy but feels underpaid or overlooked. In those situations, better compensation or clearer progression can successfully retain valuable staff.
However, if someone is already deeply disengaged or mentally committed to leaving, a counter offer often strengthens their resolve to move on rather than changing the outcome.
Insight
Counter offers are becoming increasingly common as businesses compete to retain experienced staff. Recent workforce data shows that 31% of employers facing moderate to high staff turnover responded by offering higher salaries or incentives, while 19% used flexible work arrangements to improve retention.
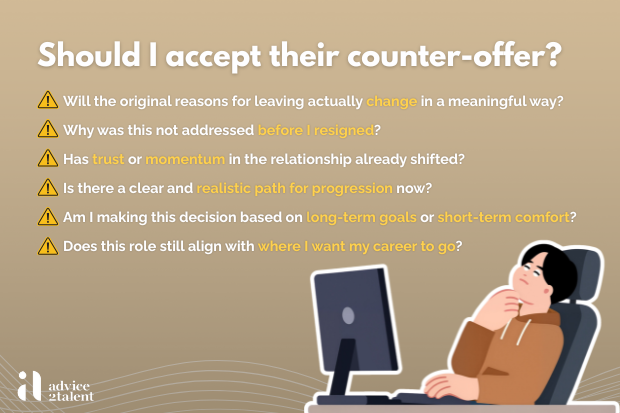
Questions to Ask Before Accepting a Counter Offer
If you are considering staying after receiving a counter offer, it helps to step back and assess it objectively.
Some key questions include:
- Will the original reasons for leaving actually change in a meaningful way?
- Why was this not addressed before I resigned?
- Has trust or momentum in the relationship already shifted?
- Is there a clear and realistic path for progression now?
- Am I making this decision based on long-term goals or short-term comfort?
- Does this role still align with where I want my career to go?
These questions help separate immediate emotion from longer-term career direction.
Leaving on Good Terms
If you decide not to take the counter offer given by your employer, the next step is handling your resignation professionally and respectfully.
Regardless of what happens next, professionalism matters.
The financial planning, mortgage broking, and accounting sectors are more interconnected than they appear.
People move between firms, reconnect in new roles, and cross paths multiple times throughout their careers.
A professional resignation should always involve:
- Clear and respectful communication
- A calm and considered approach
- No emotional decision-making in the moment
- A willingness to support a smooth transition where appropriate
It’s also important to understand your contractual obligations around notice periods. In most cases, your employment contract will outline how much notice is required when resigning.
Fulfilling your notice period professionally helps ensure a smoother transition for both you and your employer.
If there is a need to shorten your notice period – whether due to the timing of your new role or personal circumstances – it’s best to discuss this openly with your manager or supervisor rather than making assumptions.
Some employers may agree to an earlier finish date, while others may require the full notice period depending on operational needs.
Having that conversation early and ensuring both sides are aligned helps avoid unnecessary tension or misunderstandings.
If you are unsure about what is legally allowed under your contract or workplace obligations, it’s always worth reviewing your agreement carefully or seeking professional advice before making any decisions.
Even if the situation feels uncomfortable, how you leave is often remembered just as much as how you performed in the role.
Protecting Your Long-Term Career Growth
Resigning after accepting a new job offer is rarely straightforward.
Even when you are confident in your decision, a counter offer or emotional response from your current employer can create doubt.
But career decisions are rarely about short-term comfort. They are about long-term direction.
If you are currently navigating a resignation, counter offer, or career move within financial planning,
Articles You Might Also Like

Can Offshore Accountants Work in Australia? Avoiding Compliance Risks When Building an Offshore Team
As accounting talent shortages continue across Australia, more firms are turning to offshore accountants to increase capacity and support growth. But can offshore accountants legally work for Australian firms, and who remains responsible for compliance? This guide explores the regulatory obligations, liability considerations, and risk management practices firms need to understand before building an offshore accounting team.
How to Attract and Retain Top Talent: Why Salary Alone Isn’t Enough
Australian employers are facing growing talent shortages, but higher salaries alone are not solving the problem. Learn why career development, flexibility, leadership, culture, and employee experience have become critical factors in attracting and retaining top talent.
Work Abroad Or Become A Virtual Assistant? How A VA Career Can Open Global Opportunities
For years, working abroad meant relocating overseas to build an international career. Today, remote work offers another path. Discover how becoming a virtual assistant can provide global exposure, valuable professional experience, higher earning potential, and even future overseas opportunities, all without leaving home.
Is Feeding Company Information Into AI Safe? What Australian Businesses Need to Know
AI is becoming part of everyday business, but giving AI more information can also create privacy and confidentiality risks. Here’s what Australian businesses need to consider before putting company, client or employee information into AI tools.
AI in the Workplace: How Businesses are Redesigning Jobs and Roles
AI isn’t simply replacing jobs. It’s changing who does what. Discover how Australian businesses are redesigning roles, reallocating responsibilities and combining AI with human expertise to build more capable, efficient teams.
Experience vs Expertise: Which Matters More When Hiring?
Years of experience can tell you where a candidate has been, but expertise tells you what they can do. Learn how to assess both when hiring the right candidate.

2 Responses